Who earned the mining rewards?
A miner who works alone, participates in a pool, or pays a host for equipment receives different evidence of what the operation earned. Start with the legal owner and the pool or machine records. Only then decide whether a withdrawal to a personal wallet represents new income or the movement of rewards already recorded.
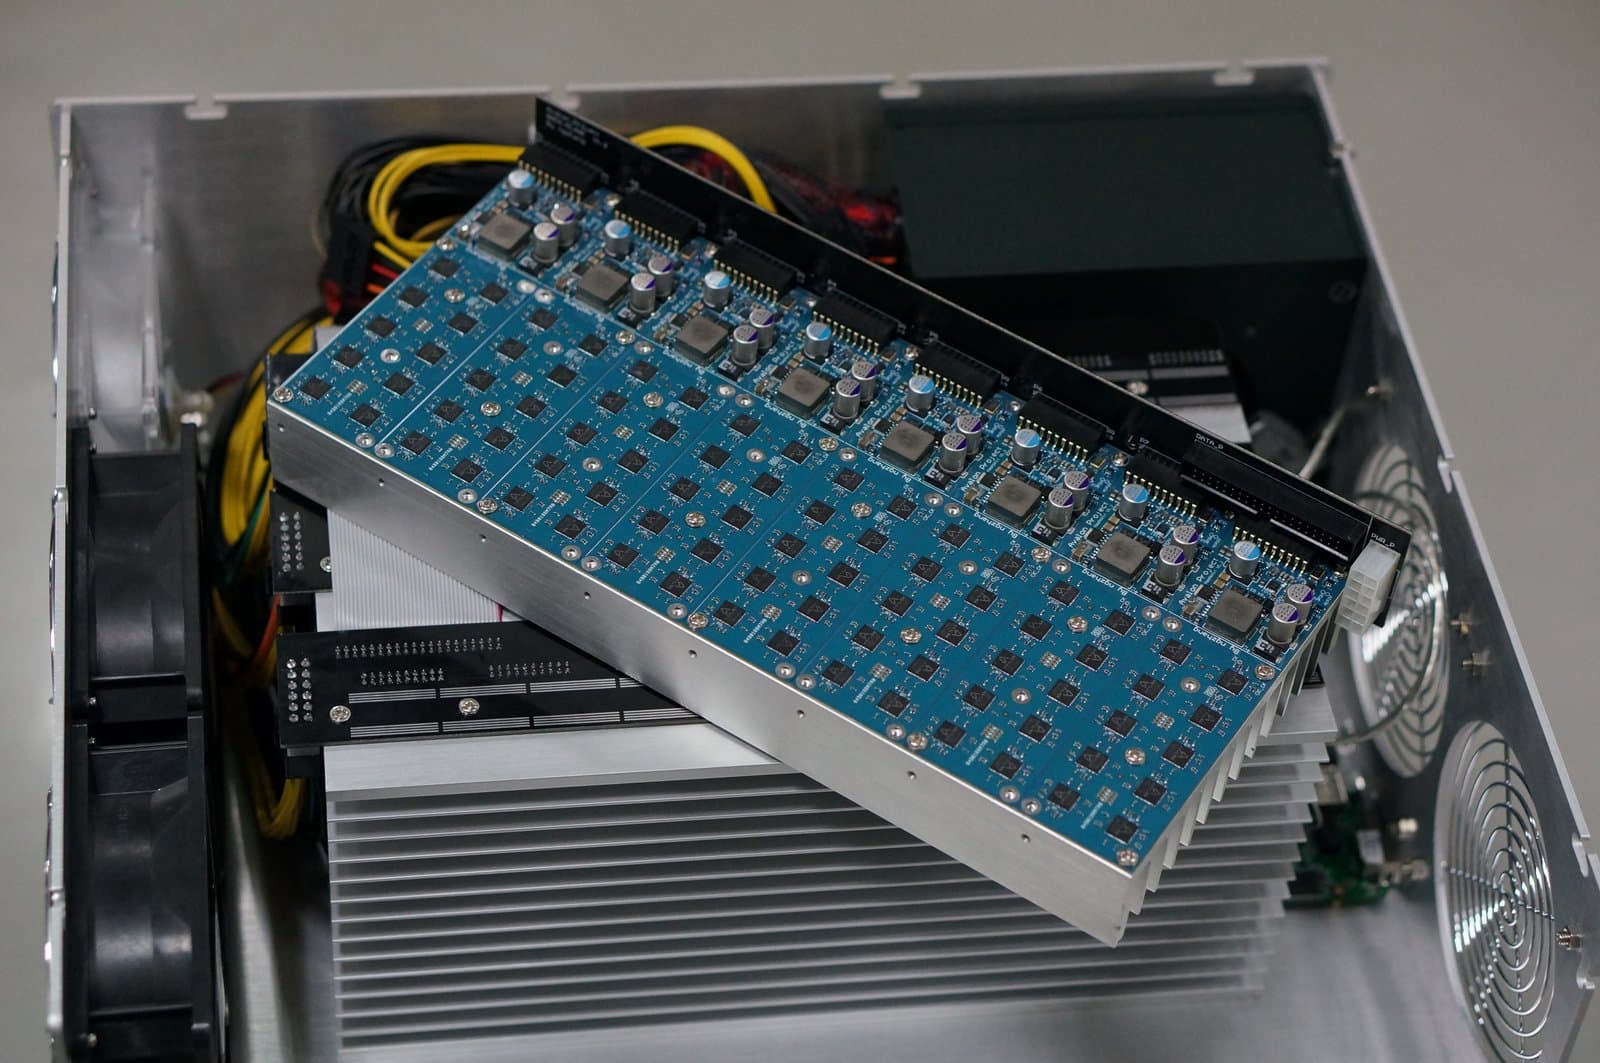
The Bitcoin developer guide distinguishes solo mining from pooled work. In the pool model it describes, the pool receives block rewards and pays participants according to their contributions and its distribution system. A pool payout is therefore not the same evidence as a coinbase output from a block the applicant claims to have mined alone. Keep the technical explanation narrow enough to match the actual activity.
The next distinction is ownership. Equipment purchased by a company, operated under a company contract and paid into a director’s wallet leaves an important question unanswered: whose asset was received? Identify the operating entity, contractual customer, pool account holder, and intended beneficiary. A personal wallet address should not silently turn company revenue into personal wealth.
Reconstruct the operation before the rewards.
Divide the history into operating periods. Record where the machines were located, who owned them, who paid the power or hosting costs, when equipment was added or removed, and which payout arrangement applied. A change of host, business partner, or pool can explain a change in the records. Treat it as a transition to document rather than forcing the whole history into one description.
Equipment invoices, serial-number schedules, hosting agreements, power bills, and contemporaneous accounts can support different parts of that account. An invoice establishes a purchase more readily than continuous operation. A hosting bill can establish a contractual relationship without proving the output of every machine. Explain what each exhibit supports instead of attaching a stack of receipts and asking the reviewer to infer the rest.
Use historical operating data when assessing whether a reward history is plausible. Present-day equipment performance is not evidence of an earlier installation’s output. Preserve the available logs and period-specific specifications, distinguish measured values from estimates, and explain downtime. An estimate can test a story for obvious inconsistencies; it should not replace actual receipt records.
Build the appropriate receipt record.
For a solo-mining claim, identify the relevant block and transaction, the output attributed to the operation, and the evidence linking that output to the claimant at the time. Keep the machine-readable transaction reference alongside the explanatory narrative. A screenshot is convenient for reading, but a cropped image alone is a weak foundation for a long history.
For a pool, preserve account exports, worker identifiers, payout settings, fees, credit entries, and withdrawals. Reconcile the opening pool balance, new credits, adjustments, payouts, and closing balance. If a payout batches several workers or periods, show how the pool ledger reaches the transaction received. A third-party address label can be a lead to investigate; it does not establish that this applicant earned the distribution.
Hosted and shared operations need the entitlement record too. Identify the contract, ownership allocation, operator deductions, and any later distribution to the individual. If the arrangement changed, retain both versions and their effective dates. Do not present all receipts arriving at a shared address as one participant’s personal income merely because that participant now controls the keys.
Reconcile a pool ledger before tracing the personal payment.
Consider a fictional small mining company owned by Noor and a business partner. It begins a month with 0.3 BTC credited in its pool account. During that month, the pool credits 1.2 BTC, deducts 0.02 BTC in recorded fees, and pays out 1 BTC. The closing pool balance should be 0.48 BTC if there are no other adjustments. This invented example tests the pool ledger’s arithmetic before any claim about personal wealth is made.
The 1 BTC payout reaches the company’s wallet. The company later sells 0.6 BTC to pay hosting expenses and retains 0.4 BTC, ignoring separate network fees only for this simplified illustration. The pool’s 0.48 BTC credit and the company wallet’s 0.4 BTC are different locations in the same economic history. Adding the full 1.2 BTC earned to both closing balances would overstate the holdings.
Noor now wants to use part of the retained Bitcoin for a personal citizenship application. Her shareholding alone does not explain the proposed transfer. The company and its advisors need to establish the lawful basis for any distribution or other payment, the approvals required, and the treatment in the accounts. The partner’s interest cannot disappear because Noor happens to hold the wallet’s signing device.
Only after that entitlement is supported can the personal source-of-funds narrative connect the company’s mining, the authorized transfer, and Noor’s proposed payment. If the company itself is an approved payer, the file should say that and show the necessary authority. The example illustrates evidence and ownership questions; it does not prescribe a distribution method or determine tax consequences.
In a real file, all fees, time-zone differences, reversals, and additional receipts would need reconciliation. Preserve the raw pool export beside the explanatory calculation. An accurate summary should remain reproducible by another reviewer without access to the miner’s memory or a live dashboard that may later disappear.
Carry the receipts through custody without double counting.
A reward schedule explains accumulation. A custody history explains where the supported holding went afterward. Link the two, then identify transfers between your own wallets, sales, exchanges, business payments, and distributions to other owners. Use consistent units and document fees. A consolidation into a new wallet is not a second earning event merely because another incoming transaction appears in an export.
Illustrative example: a company receives pool payouts, sends some Bitcoin to an exchange to pay its host, and later distributes a supported amount to its owner. The evidence needs to explain the company’s earnings, the sale, or expenditure and the authority for the distribution. The owner’s source-of-funds account begins with that entitlement; it cannot treat every company payout as personal income.
Identify the particular funds proposed for the next payment and their connection to the supported history. If mined coins were combined with purchases, gifts, or customer receipts, describe those sources separately. A fresh address does not supply a missing acquisition record. Nor should a reviewer need a seed phrase, private key or unrestricted wallet access to read the explanation.
Keep receipt, valuation, and later disposal distinct.
US federal treatment provides a specific example, not a worldwide rule. IRS Notice 2014-21, answers eight and nine, addresses mining receipts at their fair market value when received, and the circumstances in which an individual’s trade-or-business mining produces self-employment income. Those provisions do not establish the treatment of every entity, residence, or historical year.
Retain the valuation method, currency, relevant date, and underlying price evidence used in the accounts. A year-end Bitcoin price cannot silently replace a receipt-date valuation. Give the CPA the full record of receipts and later disposals, including exchanges used to fund operating costs. Where an earlier return or ledger conflicts with a reconstruction, show the discrepancy rather than rewriting one to make the file appear consistent.
The professional review should identify the applicable person, jurisdiction, and period before deciding whether any filing or correction is required. A citizenship evidence review is not a tax assessment, and a tax return is not by itself proof of every underlying mining claim. The records should support each other while their different purposes remain clear.
Make the gaps usable.
A closed pool or failed drive does not produce a replacement ledger on demand. List the missing period, the recovery attempts, the surviving records, and the proposition that remains uncertain. Archived emails, bank payments to a host, old accounts, and wallet records can corroborate parts of the history. Do not describe a corroborating item as a complete substitute when it answers a narrower question.
Separate records made during operations from later explanations. A former partner may be able to describe an arrangement from memory, but the statement should disclose that basis and its preparation date. Do not backdate a contract or ask someone to confirm facts they did not observe. An honest gap gives the recipient something to assess; manufactured precision creates another problem.
Finish with a short narrative and an exhibit index organized around the operation, entitlement, receipts, custody, and proposed use. Give the accountant and the application coordinator the same factual chronology. Ask the intended recipient which uncertainties require further work before committing to a payment date. The aim is a record that survives a change of reviewer, not a promise that every institution will accept it.
Test a missing record against the question it leaves open.
A missing hosting invoice and a missing pool statement create different gaps. The hosting invoice concerns the operating relationship and costs. The pool statement concerns credited work, deductions, and entitlement to payouts. Bank records showing payment to a host may help with the first question while leaving the second largely unanswered. Substitution should therefore be proposition-specific.
Suppose Noor retains a dated email confirming the payout address and a bank transfer for equipment, but the pool has closed. Those records can support address configuration and equipment acquisition. They do not recreate the complete pool ledger. Her reconstruction should identify the periods covered by surviving receipts and any interval supported only by a later statement or estimate.
Ask former operators or partners for records they actually hold and facts they personally know. A statement made today can explain an earlier relationship, but should give its date and basis. A detailed recollection is still a recollection. Do not convert it into a supposedly contemporaneous contract or ask someone to certify totals they cannot independently substantiate.
If the uncertainty is material to the proposed funds, discuss it with the intended reviewer before committing to an application timetable. The answer may be further reconstruction, an independent technical review or use of a separately supported source. It should not be the deletion of the uncertain period from a narrative that otherwise implies an unbroken history.
Make ongoing preservation part of operating the mine. Export statements when issued, record changes of payout address and retain the authority for company distributions. Keep a copy independent of the pool and hosting provider, with access limited to the appropriate people. That modest discipline is usually easier than reconstructing years of activity after a provider closes or a business relationship ends. It also gives the accountant a stable record instead of a changing collection of screenshots.
The whole picture
The Bitcoin Lawyer take
Start with the pool ledger and identify the legal owner of the mining operation. Then trace the amount actually paid out. Counting both a pool credit and its withdrawal would overstate the Bitcoin available.
Preserve records while the operation is running and the responsible people can still answer questions. The keys provide spending control. The contracts, pool exports, accounting, and custody history explain whose value is being spent and how it was earned. Both matter when mining wealth becomes a family’s mobility decision.